🏃
Good people keep leaving
Employees walk to competitors that offer health coverage, and every replacement costs you time, training and lost sales.
Losing good people to employers with better benefits? Dreading another premium increase? In a free 30-minute plan review, Kevin Smith compares small business health insurance options from leading carriers and shows you what fits your budget before your 2027 renewal.
You built the business. Now benefits decide who stays, who joins and how much you keep.
Employees walk to competitors that offer health coverage, and every replacement costs you time, training and lost sales.
Without a real health plan, your job offers lose to bigger companies before the interview is even over.
Employer family coverage now averages close to $27,000 a year, up about 6% in 2025 (KFF). Renewing without shopping often means paying more than you need to.
At 50 full-time employees, including part-time equivalents, ACA employer rules and IRS penalties apply. The time to plan is before you cross the line.
Many small employers never claim the Small Business Health Care Tax Credit, worth up to 50% of the premiums they pay.
Comparing carriers, networks and deductibles takes hours you don't have. So the renewal letter gets signed as-is, again.
Free. No obligation. 30 minutes with Kevin.
Health coverage is the benefit employees ask about first. For a small business, a well-designed group plan is one of the most cost-effective ways to compete for talent.
A group plan isn't just a line on the offer letter. It's protection your people feel every time they or their families need care.
Carriers need quotes, employee details and enrollment forms before coverage can start. For a January 1, 2027 effective date, that work happens in the next few weeks.
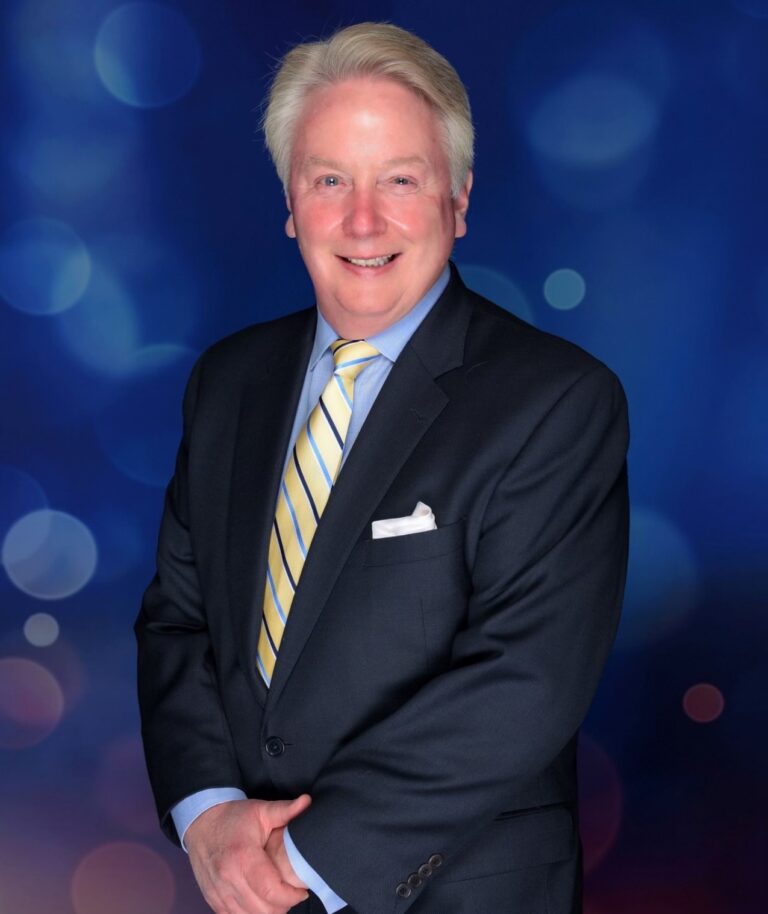
Kevin has spent more than 25 years in the health insurance industry, rising from sales associate to manager and director at a carrier before founding Advanced Benefit Designs in Doylestown in 2000.
He knows how carriers price small group plans, and he works for you, not the insurance company. You get one person who explains your options in plain English, handles the paperwork and is there when an employee has a claim question.
Pick a time that works. Tell Kevin about your team, your budget and what's not working today.
Kevin shops multiple carriers and lays out the plans side by side: premiums, deductibles, networks and tax credits.
You pick the plan. ABD handles the applications and employee enrollment, and stays with you at every renewal.
Compare plans from leading carriers, including
It depends on your team's ages, ZIP codes, the plan design you choose and how much of the premium you decide to pay. Many owners pay at least half of the employee's premium and let employees add family members. In a free plan review, Kevin compares real quotes from several carriers so you can see the numbers side by side.
Small group plans are built for businesses with just a few employees up to 50. Carrier rules on minimum size and participation vary, so ABD checks which options fit your exact headcount.
Under the Affordable Care Act, employers with 50 or more full-time employees, including full-time equivalents, are Applicable Large Employers. They must offer affordable, minimum-value coverage to at least 95% of full-time staff or risk IRS penalties, and they take on extra reporting. Moving from small group to large group can also change how your rates are set, so plan the transition before you cross the line.
Yes. The Small Business Health Care Tax Credit can cover up to 50% of the premiums you pay (35% for tax-exempt employers) for two consecutive years if you have fewer than 25 full-time-equivalent employees, pay average wages under the IRS limit, pay at least 50% of employee premiums and buy through the SHOP Marketplace. Employer premium contributions are also generally deductible as a business expense. Confirm the details with your tax advisor.
No. The plan review is free, and brokers are typically paid by the insurance carrier, so you do not pay more for your plan by working with ABD.
Now. Carriers need applications, census details and employee enrollment before the start date, and that takes several weeks. Book your plan review this week to leave time to compare options and enroll your team.
Advanced Benefit Designs works with small businesses across Pennsylvania, from our office in Doylestown, Bucks County.
Choose a time below. You'll get a calendar invite right away. No cost, no obligation.
Calendar not loading? Open Kevin's calendar in a new tab